
Procedure for Transferring Commercial Land Use Right Certificates may expose enterprises to transaction delays, unexpected tax obligations, and rejected registration dossiers when transfer conditions are not properly verified. Under the Law On Land, the transfer must be registered as a change in land records within 30 days from the effective transaction date. Commercial land leased with annual rental payments is subject to different transfer limitations from land leased through a one-time payment arrangement.
Long Phan Consulting assists businesses in reviewing transfer eligibility, structuring the transaction, preparing the required documents, and coordinating the registration process to reduce procedural and commercial risks.
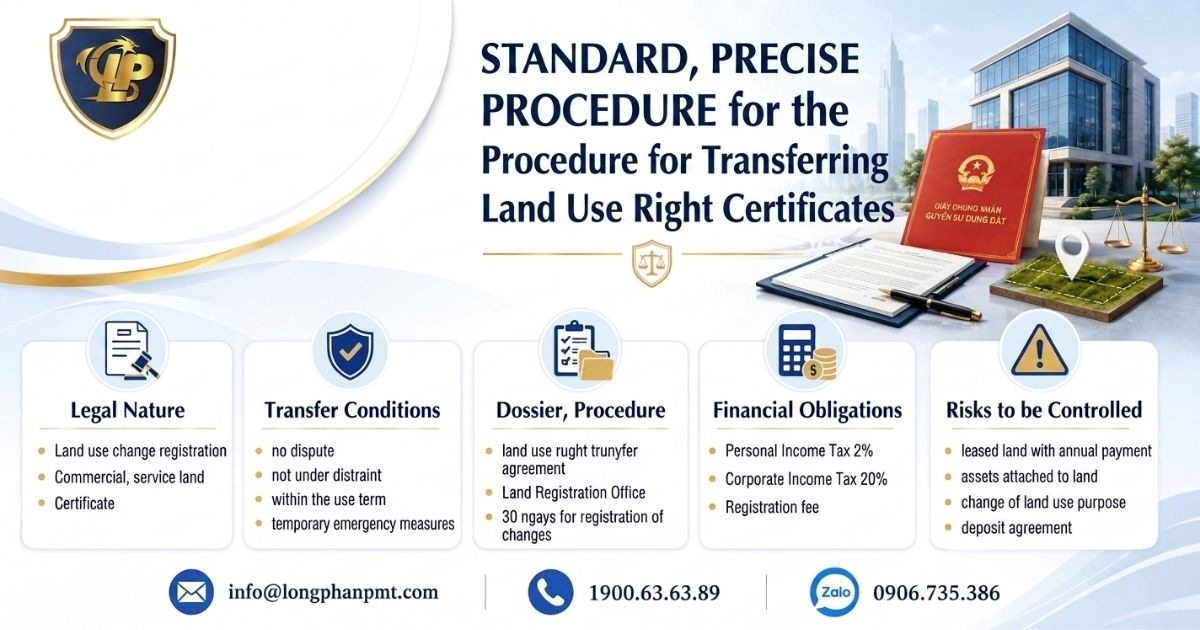
Commercial and service land should not be evaluated as a standard “real estate purchase.” For investors, the most significant risk lies in confusing the right to transfer land use rights with the right to dispose of assets attached to the land.
Commercial and service land belongs to the non-agricultural land group, utilized for business establishments, trade services, accommodation facilities, representative offices, warehouses, or infrastructure serving commercial activities. This classification is formally recognized under Point dd, Clause 3, Article 9 of the 2024 Land Law.
Decree 102/2024/NĐ-CP provides a more granular description of the scope for commercial and service land usage. This category encompasses land used for constructing business facilities, trade services, and other infrastructure supporting commercial operations, pursuant to Point b, Clause 5, Article 5 of Decree 102/2024/NĐ-CP. Consequently, the transfer procedure depends on more than just the transfer contract. Enterprises must verify the intended land-use purpose, remaining tenure, and the specific mechanism through which the State allocated or leased the land.
Before executing a contract, the transferee must conduct a legal audit of the land plot as a mandatory due diligence step. Failing to meet even one requirement may lead to the rejection of the registration of land fluctuations or significant transaction delays.
Fundamental conditions include:
These conditions are established under Clause 1, Article 45 of the 2024 Land Law. In B2B transactions, these serve as the minimum audit criteria prior to providing deposits, making payments, or receiving the site.
The most critical control point is the method of land rental payment. While both categories are classified as commercial and service land, the disposal rights held by the enterprise differ significantly.
| Legal Criteria | Land Leased with One-time Rental Payment | Land Leased with Annual Rental Payment |
| Transferability | Transferable, provided statutory conditions are met | Land use rights cannot be transferred as a one-time payment property |
| Audit Focus | LURC, tenure, disputes, seizure, financial obligations | Attached assets, lease rights, construction conditions, and prepaid compensation |
| Transaction Risks | Improper dossiers or outstanding financial duties delay registration | High risk of misclassification as a standard LURC transfer |
| Primary Legal Basis | Point b, Clause 1, Article 33 of the 2024 Land Law | Point c, Clause 1, Article 34 and Clause 2, Article 46 of the 2024 Land Law |
For land leased with annual payments, enterprises cannot “transfer the LURC” in the sense of transferring land use rights. The only viable path is to sell the assets attached to the land and the lease rights within the rental contract, provided legal conditions are satisfied.
Pursuant to Clause 2, Article 46 of the 2024 Land Law, assets must be legally established and constructed in accordance with detailed planning and approved investment projects. Furthermore, the enterprise must have prepaid the compensation, support, and resettlement costs that have not yet been fully deducted by the State from the land rent.
Investors should not rely solely on the term “commercial and service LURC” in sales dossiers. The actual transaction value lies in the transferability of the rights, the remaining usage tenure, and the ability to register land fluctuations with the land administration authority.
If a land plot is subject to annual rental payments but the deposit agreement commits to a transfer of land use rights, the risk of losing the deposit and entering a contractual dispute is extremely high. Enterprises must review the LURC, the land allocation decision, or the land lease contract before signing any payment agreements.
Once a land plot meets all transfer conditions, the focus shifts to standardizing the dossier and ensuring timely registration of land fluctuations. For commercial and service land, a single error in the dossier can derail the handover of the premises, the recognition of assets, and the accounting of investment costs.
The dossier must accurately reflect the nature of the transaction as a transfer of land use rights, rather than a standard sale of movable assets. Pursuant to Article 502 of the 2015 Civil Code, the contract for the transfer of land use rights must be established in writing and strictly adhere to land law procedures.
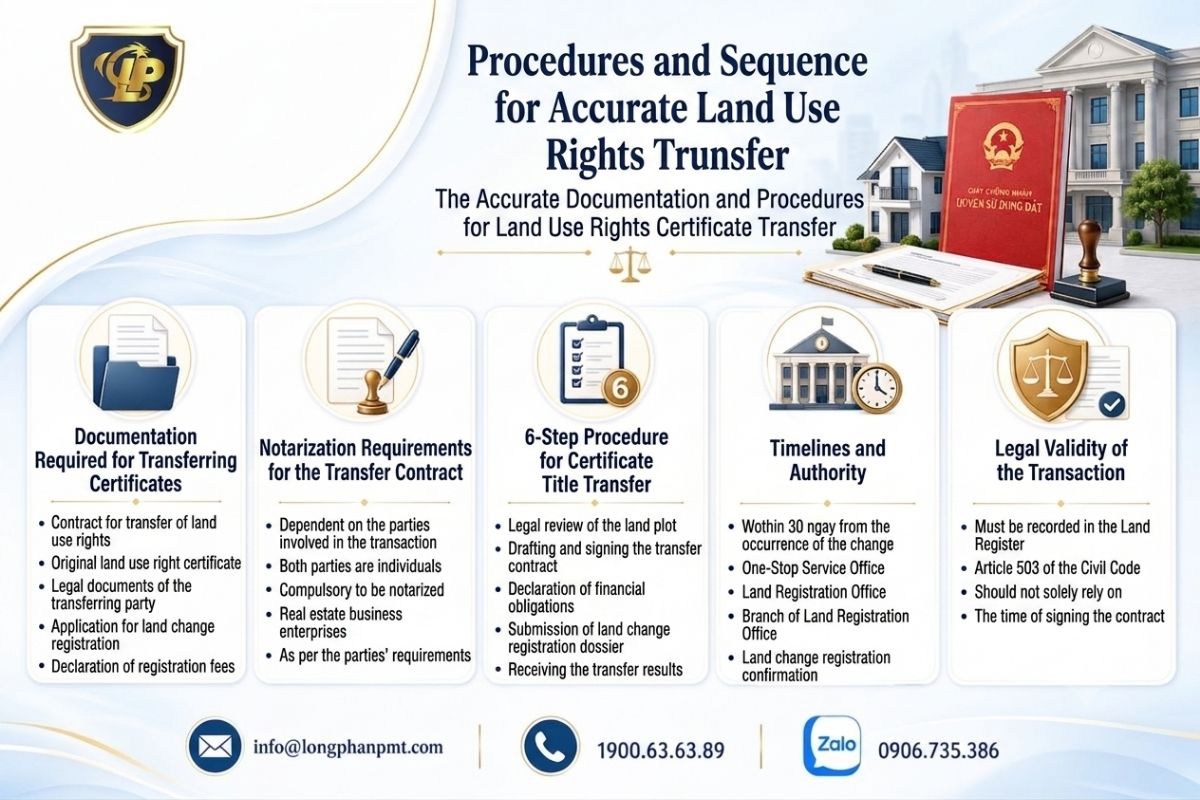
Enterprises should prepare the following documentation:
Clarity regarding the parties, assets, and financial obligations minimizes the likelihood of administrative requests for supplementary documentation. Enterprises should reconcile land records with asset records before contract execution.
The requirement for notarization depends on the participants involved. If both parties are individuals, the contract must be notarized or authenticated, pursuant to Clause 5, Article 44 of the 2023 Law on Real Estate Business. If one party is a real estate business entity, notarization is conducted at the discretion of the parties, per Clause 4, Article 44 of the 2023 Law on Real Estate Business. Regardless of legislative flexibility, enterprises should prioritize validly certified contracts as a primary evidentiary safeguard in the event of disputes over payments, site handovers, or registration of fluctuations.
The transfer procedure is essentially a registration of land fluctuations due to the transfer of land use rights. Enterprises must file the application within 30 days from the date the fluctuation arises, per Clause 3, Article 133 of the 2024 Land Law.
Transactions only achieve full legal validity upon entry into the registration book, pursuant to Article 503 of the 2015 Civil Code; therefore, companies should not rely solely on the date of contract signing to confirm their rights.
Summary of the required dossier, notarization requirements, and the 6-step procedure for registering land fluctuations with the competent authority
Planning for the costs associated with transferring commercial and service land must occur prior to contract execution. Improper allocation of tax liabilities can lead to delays in the registration of fluctuations, payment disputes, or adverse impacts on investment cash flow.
In B2B transactions, costs extend beyond the transfer price. Enterprises must clearly delineate the obligations of each party to prevent ambiguous contractual terms, particularly when one party is a professional real estate business.
| Party | Common Financial Obligations | Focus for Control |
| Transferor (Individual) | Personal Income Tax (PIT) on real estate transfer | Accurate determination of transfer price and tax liability |
| Transferor (Enterprise) | Enterprise Income Tax (EIT) on real estate transfer | Accounting for revenue, costs, and taxable income |
| Transferee | Registration fees and appraisal service charges | Cash flow preparation prior to registration filing |
Financial responsibilities should be explicitly stated within the transfer contract. This serves as the primary basis for resolution should tax authorities request supplementary documentation or if a party delays payment.
When the transferor is an individual, Personal Income Tax (PIT) on real estate transfers is calculated at a rate of 2% of the transfer price, pursuant to Clause 1, Article 14 of the 2025 Law on Personal Income Tax. For investors acquiring business premises, a common risk involves price discrepancies between the contract and actual cash flow. Such inconsistencies can delay tax declarations and extend the timeline for the registration of fluctuations. Transferees should mandate that the seller provide tax information during the deposit phase to maintain control over the filing progress and avoid financial uncertainty.
When the transferor is an enterprise, income from the real estate transfer is processed under the Enterprise Income Tax (EIT) regime. The standard tax rate is 20%, pursuant to Clause 1, Article 10 of the 2025 Law on Enterprise Income Tax.
Income derived from real estate transfers must be accounted for according to its true nature. These earnings are categorized under “other income,” per Point b, Clause 2, Article 3 of the 2025 Law on Enterprise Income Tax. Executive management and accounting departments should forecast tax liabilities prior to finalizing the sale price. If negotiations are based solely on net price without accounting for tax obligations, the profit margin of the deal may be significantly compromised.
Financial obligations are the most common bottleneck in the transfer of commercial and service land. Dossiers may be contractually complete but stalled if taxes, fees, and related vouchers remain outstanding. Key risks include delays in tax declaration, disagreements regarding the liable party, and a lack of documentation, which may trigger official sanctions or, in extreme cases, land recovery proceedings pursuant to Clause 6, Article 81 of the 2024 Land Law. For high-value transactions, tax obligations must be integrated into the payment schedule and disbursement conditions.
The primary risk associated with commercial and service land lies not in the transfer price, but in the capability of the land administration authority to record the land fluctuation. A transaction supported by a signed contract and full payment may still be suspended if the asset fails to satisfy the legal conditions required for business operation.
Enterprises must identify risks before placing a deposit or disbursing capital. For existing commercial real estate, the asset must hold a valid Land Use Rights Certificate (LURC), be free from transaction bans, and have its information publicly disclosed, per Clause 1, Article 14 of the 2023 Law on Real Estate Business.
Common errors include:
For business premises, the deal value typically encompasses both the land use rights and the structures built upon them. If these assets are not recorded, the registration authority may demand supplementary documentation or refuse to update the ownership records. Pursuant to Clause 6, Article 13 of the 2023 Law on Real Estate Business, real estate sale contracts must be written and clearly delineate private versus shared areas.
When assets are not finalized or updated on the LURC, enterprises should proceed as follows:
This approach prevents the situation where an enterprise takes possession of premises but fails to secure the legal recognition of the asset ownership.
A commitment to “convert to residential land” within a deposit agreement for commercial and service land is a high-risk signal. Land use purpose conversion depends entirely on zoning, land use planning, and the approval of competent authorities, not the promises of the seller. Enterprises should view the conversion condition as an independent legal requirement. If this condition remains unverified, the deposit must be tied to clear mechanisms for repayment, penalties, and explicit termination rights.
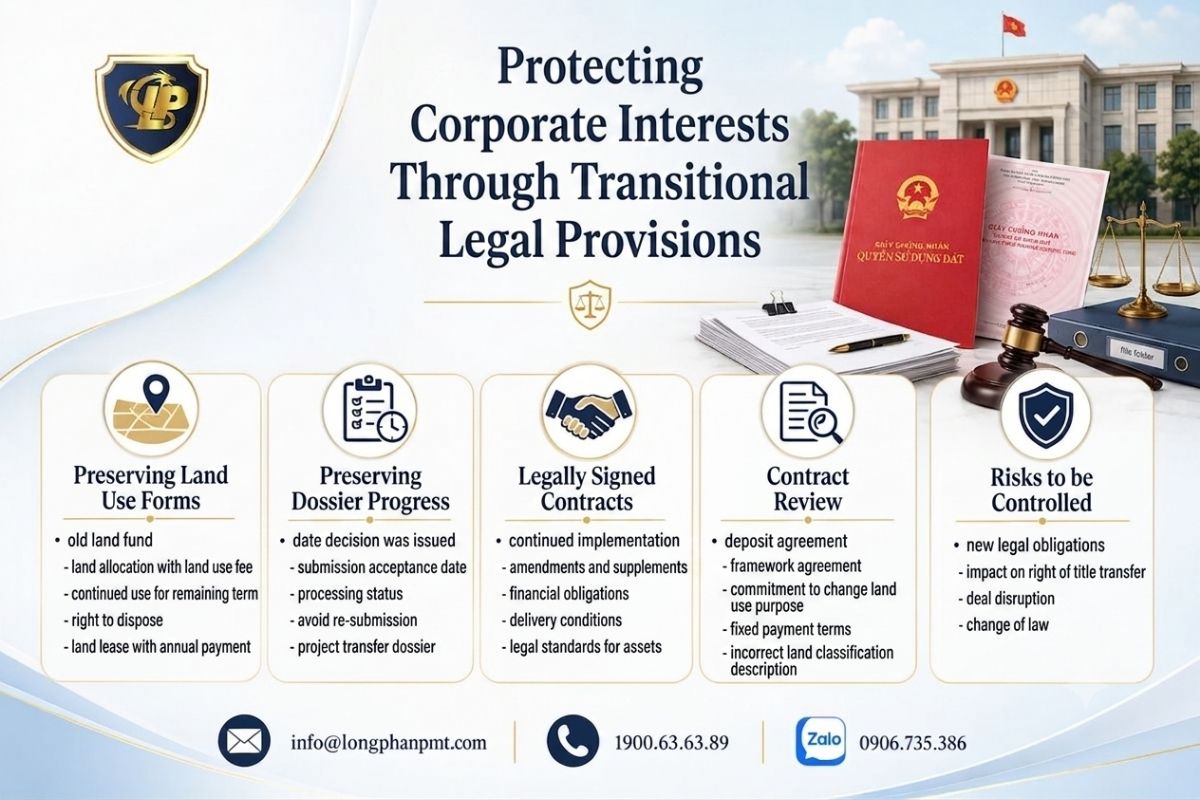
Transitional regulations are significant for enterprises currently holding legacy commercial and service land or finalizing transfer dossiers. Proper application allows companies to safeguard their capital structure, transaction timelines, and the validity of executed contracts.
Enterprises that were allocated land with the payment of land use fees by the State prior to the effective date of new legislation are not obligated to immediately transition to a land lease model. Land use rights may continue for the remaining tenure, per Clause 2, Article 255 of the 2024 Land Law. This rule provides a safe harbor for enterprises holding commercial and service land assets previously acquired via a one-time fee, allowing them to maintain more favorable disposal rights compared to the annual land rental mechanism. Enterprises should note the expiry of the land tenure, as future extensions may trigger changes in financial obligations and transfer rights.
Land dossiers currently in the transitional phase should be categorized by the date of issuance, reception, and current processing status. Proper classification prevents redundant procedural requirements. Essential transitional rights include:
For pending or ongoing transactions, contract content and formats must adhere to current standards. Per Point b, Clause 1, Article 688 of the 2015 Civil Code, new regulations may be applied if the transaction aligns with the current legal framework. Enterprises should scrutinize terms prone to invalidation or dispute, such as unsubstantiated commitments to change land use purpose, payment schedules detached from the registration of fluctuations, or descriptions that confuse land types. A prudent strategy is to avoid signing supplementary addendums before conducting a comprehensive structural audit of the transaction.
Visuals highlighting transitional regulations to assist businesses in maintaining project timelines, contract validity, and disposal rights over legacy land assets.
Procedures for transferring commercial and service land require the simultaneous management of land eligibility, contractual structure, tax obligations, and the registration of fluctuations. Long Phan Consulting Company assists enterprises and investors in mitigating transaction risks through a rigorous process of due diligence, negotiation, and representation, tailored to the specific needs of each dossier. Our mandate extends beyond mere filing to the comprehensive protection of your ability to finalize the transaction.
For high-value transactions, we strongly recommend performing legal due diligence prior to the initial disbursement. To have your land use rights certificate, deposit agreements, or asset dossiers evaluated by our specialists, please send your materials via Email to info@longphanpmt.com or contact our Zalo at +84 906 735 386.
The process of transferring ownership of commercial and service land often involves risks due to insufficient checks by businesses before making a deposit. The following FAQs focus on the conditions for registering land use changes, land lease forms, tax obligations, and transaction validity to help investors make safer decisions.
Businesses need to verify the eligibility for land transfer before signing a contract or making a payment. The land plot must have a land use certificate, be free from disputes, not be subject to seizure, have a valid period of use, and not be subject to any temporary emergency measures. This is the minimum legal barrier to prevent the land registration application from being blocked at the land authority, according to Clause 1, Article 45 of the 2024 Land Law.
Commercial and service land leased with annual rent payments cannot be transferred to a new owner like land leased with a one-time payment. Businesses can only sell assets attached to the land and lease rights if the assets were legally created, constructed in accordance with the detailed plan and approved project, and meet the conditions of the advance compensation paid. This mechanism is stipulated in Clauses 1 and 2 of Article 46 of the 2024 Land Law.
Businesses must register changes no later than the latest deadline.30 days from the date of the change, usually the date the transfer contract is signed. Delaying the procedure can slow down the time when the rights are recorded on the Certificate of Ownership and affect the plan for exploiting the property. This deadline is established in Clause 3, Article 133 of the 2024 Land Law.
Whether a transfer contract requires notarization depends on the parties involved. If both parties are individuals, the contract must be notarized or authenticated. If one party is a real estate business, notarization is done according to the needs of the parties. This distinction is stipulated in Clauses 4 and 5 of Article 44 of the 2023 Law on Real Estate Business.
An individual transferring commercial or service land is generally subject to personal income tax at 2% of the transfer price. The acquiring enterprise should clearly allocate responsibility for declaration and payment in the contract because an unresolved tax obligation may delay registration of the change. The 2% rate is stated in Clause 1, Article 14 of the 2025 Personal Income Tax Law.
Businesses transferring commercial real estate must account for the revenue from the transaction and apply corporate income tax at the applicable rate.20%Tax payments should be anticipated before finalizing the transfer price, as tax obligations can alter the profit margin of the transaction. Tax rate20%as stipulated in Clause 1, Article 10 of the Corporate Income Tax Law 2025
A land use rights transfer transaction is not fully completed simply because the parties have signed a contract. Businesses must draw up a written land use rights transfer contract in the correct order, and the transaction only officially takes effect from the time it is recorded in the register. The principles regarding contract form and registration validity are established in Articles 502 and 503 of the 2015 Civil Code.
Executing the procedure for transferring commercial land use rights in Vietnam requires a meticulous assessment of land eligibility, rental modalities, and existing financial obligations, rather than a standard property acquisition. Secure your commercial real estate interests by engaging the expert team at Long Phan Consulting Company for professional due diligence and transactional representation. For expert guidance and to ensure your land transfer complies with all regulatory mandates, contact our Hotline at1900636389
📚 This article has been professionally reviewed based on the following legal documents: