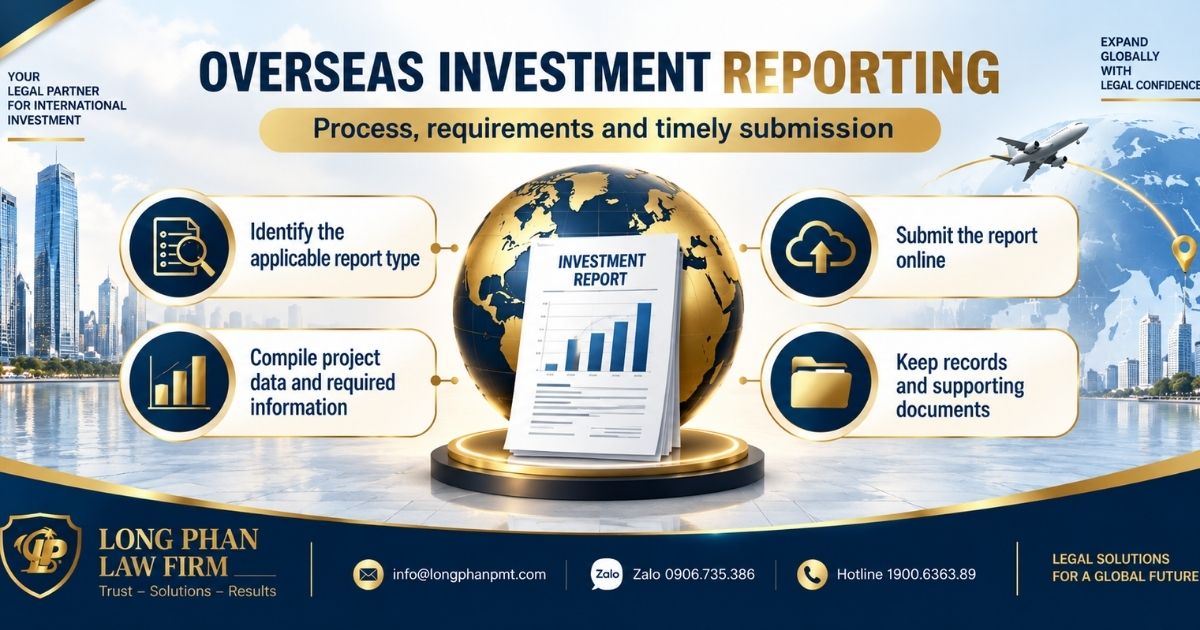

Missing reporting deadlines for FDI investment activities can cause the project’s implementing economic organization to be recorded for compliance breaches. This may affect procedures for amending the Investment Registration Certificate (IRC), increasing capital, or transferring the project. Under the Law on Investment and Decree No. 96/2026/ND-CP, enterprises must control periodic reporting obligations through the National Investment Information System, with accurate forms, consistent data, and timely submissions.
Early compliance review helps reduce administrative penalty risks and lengthy explanation procedures with support from Long Phan Consulting.
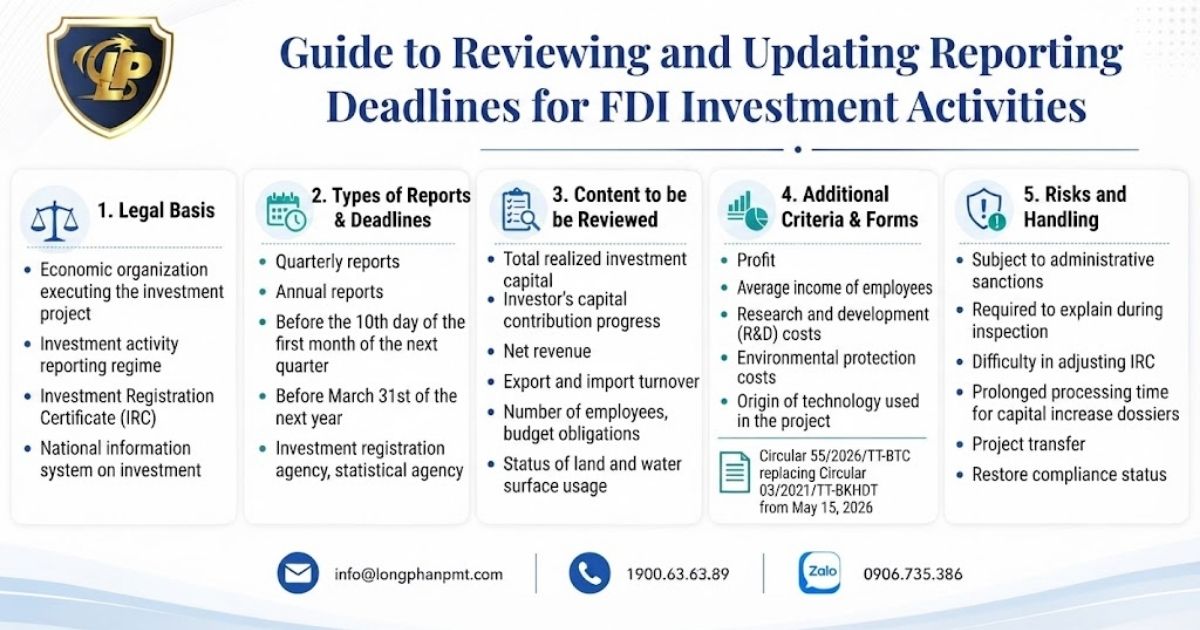
Important legal note:
Economic organizations implementing investment projects should not perceive investment reporting as a peripheral administrative task. It is a mandatory compliance obligation throughout the project’s lifecycle, directly impacting the legal standing of the Investment Registration Certificate (IRC).
For FDI enterprises, managing periodic reports serves as the foundation for preparing dossiers to adjust projects, increase capital, modify investment objectives, or execute transfer transactions. The 2025 Law on Investment serves as the fundamental legal basis governing investment activities in Vietnam.
Submitting reports on time allows the investment registration authority to monitor project implementation status, investment capital, and actual operational levels. For FDI enterprises, this is a form of risk management data rather than a mere periodic form.
Key reasons why you must conduct regular reviews include:
Failure to submit project implementation status reports may not immediately result in the loss of the IRC, but it easily creates bottlenecks when adjustment dossiers are vetted. The 2025 Law on Investment is the core legal basis for management agencies to assess the project implementation process.
FDI enterprises must build a reporting schedule based on specific obligation groups rather than processing reports only when prompted by the system or management authorities. Decree No. 96/2026/NĐ-CP, detailing and guiding the implementation of several articles of the Law on Investment, serves as the basis for establishing the investment activity reporting regime.
Reports should be categorized from the outset as follows:
Proper categorization helps legal, accounting, and project management departments avoid last-minute data aggregation. Reports must ensure consistency with information submitted to the investment registration authority and local statistical offices, pursuant to Decree No. 96/2026/NĐ-CP.
As of 2026, FDI enterprises must review all reporting forms currently in use. Continued reliance on outdated templates may trigger requests for corrections, supplements, or additional data justifications from authorities.
Transition milestones must be controlled as follows:
Enterprises must download, store, and manage new templates from the official sources published by management agencies. Circular No. 55/2026/TT-BTC, which prescribes forms for documents and reports related to investment activities in Vietnam and investment promotion, serves as the direct basis for this transition phase.
FDI enterprises must manage investment reporting as a mandatory compliance schedule rather than an internal accounting task. Each missed deadline increases the risk of scrutiny when adjusting the Investment Registration Certificate (IRC), increasing capital, or transferring projects.
The focus of this section is three-tier control: submission deadlines, data verification, and online filing methods. Articles 94, 96, and 97 of Decree No. 96/2026/NĐ-CP are the primary legal bases that the legal, accounting, and project management departments must monitor regularly.
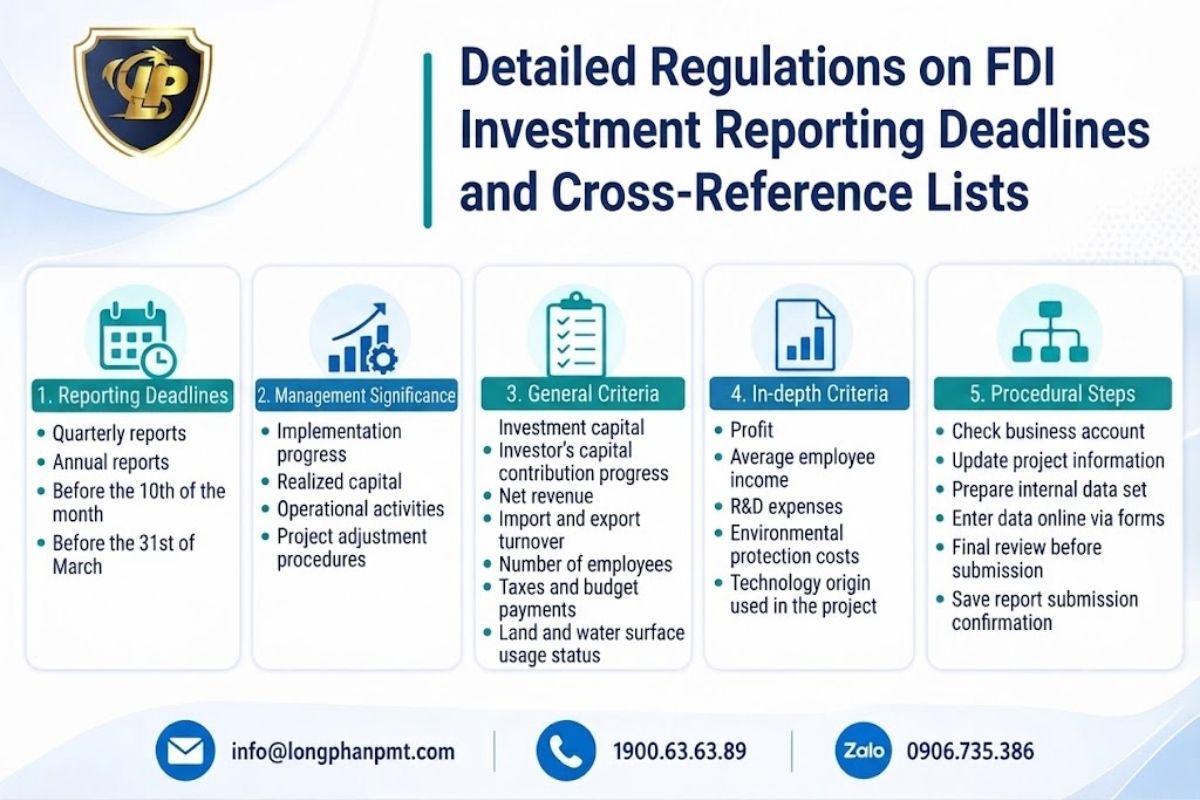
Enterprises should pin their reporting schedule at the start of the fiscal year to avoid last-minute processing. For FDI projects, the two critical milestones are the quarterly and annual reports on investment project implementation.
| Report Type | Deadline | Governance Significance |
| Quarterly Report | Before the 10th day of the first month of the following quarter | Updates progress, disbursed capital, operations, and period-specific project indicators. |
| Annual Report | Before March 31st of the following year | Consolidates annual data for state management, inspections, and project adjustment procedures. |
Enterprises should set internal alerts at least one reporting cycle in advance. Article 94 of Decree No. 96/2026/NĐ-CP defines the deadlines for both quarterly and annual reports for economic organizations implementing investment projects.
Before filing, enterprises must reconcile data between investment reports, financial statements, tax records, and internal operational data. Discrepancies in revenue, capital, or labor can lead to prolonged explanatory requirements during regulatory audits.
Common indicators subject to review for each reporting period include:
For annual reports, enterprises must further update:
These indicators must be standardized before submission. Decree No. 96/2026/NĐ-CP provides the framework for the content of investment project implementation reports for economic organizations.
FDI investment reporting must be managed as a structured process with role-based access, audit trails, and data verification. Login accounts should not be shared across departments without control, as inaccurate data can create future compliance risks.
Standardized internal procedures should include:
Article 96 of Decree No. 96/2026/NĐ-CP regulates online reporting via the National Investment Information System, while Article 97 details the account issuance mechanism for economic organizations to execute periodic reporting.
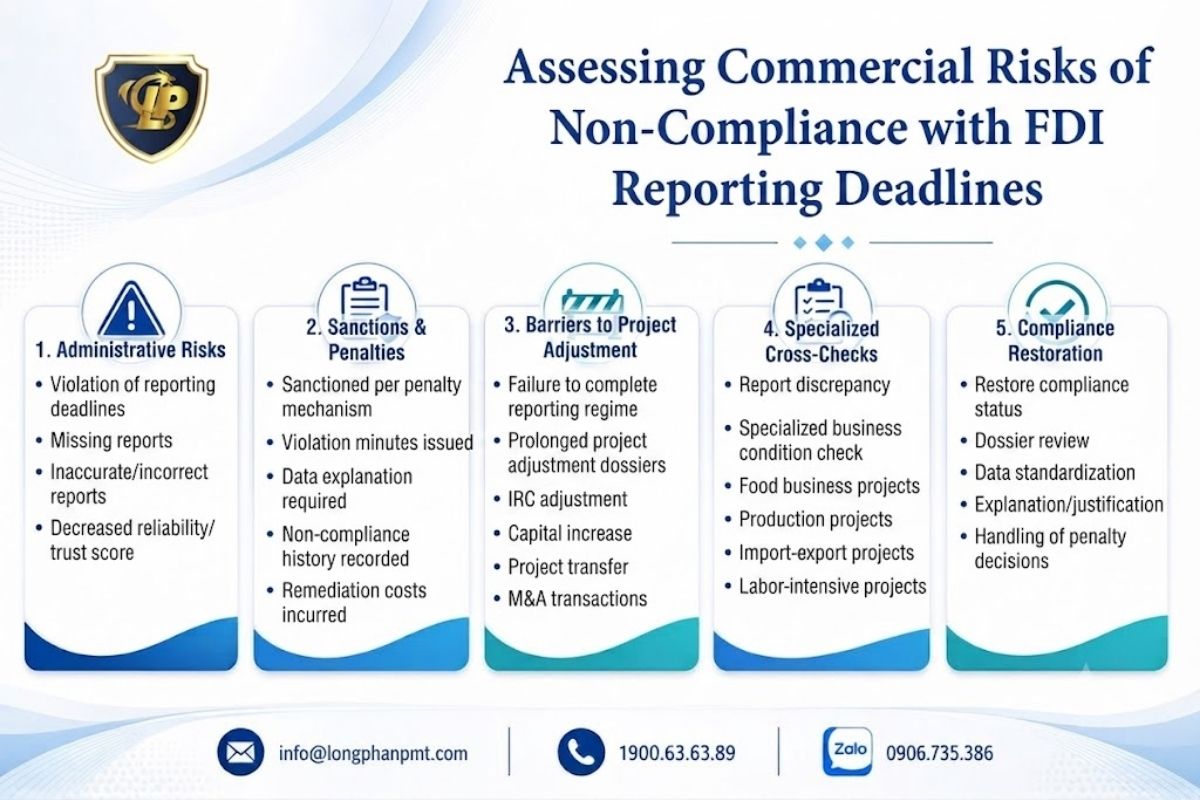
Violating reporting deadlines creates risks that extend beyond administrative sanctions. For FDI enterprises, missing reports or submitting inaccurate data undermines the credibility of the project in the eyes of regulatory authorities.
The highest risks typically arise when enterprises need to adjust their Investment Registration Certificate (IRC), increase capital, extend timelines, transfer projects, or prepare for M&A transactions. In such instances, the historical reporting compliance record becomes a critical verification data point.
Enterprises that submit reports late, fail to report, or report inaccurate data are subject to administrative penalties under the field of planning and investment. This risk must be assessed early, as violation records may negatively influence subsequent administrative procedures.
Common risk groups include:
Decree No. 122/2021/NĐ-CP provides the framework for handling violations concerning investment reporting obligations.
Incomplete investment reporting can stall project adjustment dossiers due to requirements for supplements or explanations before new requests are considered. This represents a significant commercial risk for enterprises needing capital increases or project restructuring.
| Violation Behavior | Consequent Procedural Bottleneck |
| Late submission of quarterly or annual reports | IRC adjustment dossiers may be subject to compliance status scrutiny. |
| Inconsistent disbursed capital data | Procedures for capital increases or schedule adjustments may face deeper audit. |
| Non-updated revenue, labor, or tax obligations | Authorities may require reconciliation with financial statements and tax records. |
| Missing data on land, water surface, or technology | Project transfer or M&A transactions may trigger supplementary appraisal requests. |
Enterprises preparing for M&A or project scale adjustments should restore compliance status before submitting primary dossiers. The 2025 Law on Investment serves as the foundational basis for authorities to assess the project implementation process.
Inaccurate reporting can lead to cross-audits of specialized business conditions, particularly for projects in sensitive sectors. When authorities detect abnormal data, the scope of the inspection may expand beyond the investment report itself.
Groups requiring heightened caution include:
Food business operations fall under the specialized management of the Ministry of Industry and Trade, the Ministry of Agriculture and Rural Development, and the Ministry of Health. Pursuant to Item 44, Appendix IV of the 2025 Law on Investment, enterprises must maintain these conditions throughout their operational lifespan.
The FDI investment reporting regime requires close coordination between legal, accounting, human resources, and project management teams. Long Phan Consulting Company assists clients in managing reporting obligations through a risk-preventive approach, standardizing data, and safeguarding the enterprise’s eligibility for future Investment Registration Certificate (IRC) adjustments.
This service is designed for economic organizations implementing investment projects that need to maintain a stable compliance status. Our focus is not only on filing reports but on resolving data discrepancies before they trigger inspections or hinder M&A transactions.
Legal due diligence assists enterprises in identifying compliance gaps before increasing capital, transferring projects, or preparing for M&A. This is a critical step when investment reports show inconsistencies with internal financial statements.
Long Phan Consulting Company performs the following core tasks:
The audit results serve as the basis for the management board to decide on supplemental submissions, data adjustments, or proactive explanatory briefings. This approach helps minimize reactive risks during regulatory audits.
Online report filing must be managed as a structured legal process with comprehensive audit trails. Errors in account access, reporting templates, or data entry can lead to multi-stage requests for clarification.
Long Phan Consulting Company supports enterprises in the following:
This representative service is tailored for enterprises managing multiple projects, outstanding reporting periods, or those lacking internal legal departments. Standardizing the process minimizes the risk of missing deadlines and reduces reliance on manual processing.
Enterprises that have missed reporting deadlines should prioritize restoring compliance status before initiating new procedures. Uncoordinated supplemental filings can inadvertently expose further discrepancies in capital, revenue, or tax obligations.
Long Phan Consulting Company implements remediation plans tailored to each case:
For projects undergoing M&A, addressing reporting obligations early helps reduce risks of price renegotiation, payment retention, or prolonged due diligence by buyers. Enterprises may submit their IRC, previously filed reports, and project dossiers via Email: info@longphanpmt.com or Zalo/WhatsApp: +84 906 735 386 for a preliminary evaluation by Long Phan Consulting Company.
Risks related to deadlines for reporting FDI activities often arise when businesses need to amend their Investment Regulatory Commission (IRC), increase capital, or prepare for project transactions. The questions below focus on compliance bottlenecks, reporting data, and online submission methods to help businesses manage their post-licensing obligations.
Foreign direct investment (FDI) enterprises are required to submit quarterly reports, annual reports, reports requested by investment management agencies, and reports for inspection, auditing, or project adjustments. These reports reflect the project’s implementation status, disbursed capital, revenue, import and export activities, labor, budgetary obligations, and land use. Economic organizations implementing investment projects must report to the investment registration agency and the local statistics agency in accordance with Article 94 of Decree No. 96/2026/ND-CP.
The quarterly report of an FDI project must be submitted before the 10th of the first month of the following quarter. Businesses should lock internal data before this deadline to avoid discrepancies in capital, revenue, or labor when entering the report. The deadline before the 10th of the first month of the following quarter is stipulated in Article 94 of Decree No. 96/2026/ND-CP.
The annual report on the implementation of the investment project must be submitted before March 31st of the following year. Businesses need to further review profits, average employee income, R&D costs, environmental protection costs, and the origin of the technology. The deadline of March 31st of the following year is stipulated in Article 94 of Decree No. 96/2026/ND-CP.
Foreign direct investment (FDI) enterprises must submit investment reports online through the National Investment Information System. Economic organizations implementing investment projects need to use the assigned account to submit periodic reports. The method of submitting online reports is stipulated in Article 96 of Decree No. 96/2026/ND-CP, while the mechanism for granting accounts is recorded in Article 97 of Decree No. 96/2026/ND-CP.
From May 15, 2026, FDI enterprises need to review and use the investment reporting forms according to Circular No. 55/2026/TT-BTC. Enterprises should not continue using the old forms under Circular 03/2021/TT-BKHĐT to avoid requests for revisions or further explanations. The new system of forms is adjusted according to Circular No. 55/2026/TT-BTC, which stipulates the forms for documents and reports related to investment activities in Vietnam and investment promotion.
Discrepancies between revenue figures in investment reports and financial statements may lead to requests for clarification when regulatory authorities review the records. Businesses need to simultaneously verify net revenue, implemented capital, capital contribution progress, import and export turnover, labor, taxes, and land use status before submitting the report. The content of the investment project implementation report is governed by Article 94 of Decree No. 96/2026/ND-CP.
Failure to complete the investment reporting requirements may prolong procedures for adjusting the Investment Regulatory Commission (IRC), increasing capital, extending the project timeline, or transferring the project. The investment registration authority has grounds to request the enterprise to explain the project implementation status before considering new applications. The reporting obligations of economic organizations implementing investment projects are established according to Article 94 of Decree No. 96/2026/ND-CP and are linked to the management of investment activities under the 2025 Investment Law.
Adherence to FDI investment reporting deadlines is a mandatory compliance benchmark for economic organizations, especially when seeking IRC adjustments, capital increases, or project transfers. Managing timely submissions, accurate templates, and consistent data helps mitigate risks of penalties, protracted explanatory procedures, and negative assessments during regulatory inspections. Enterprises should immediately review their reporting schedules, system accounts, and project data; please contact our Hotline at 1900636389 for timely support from Long Phan Consulting Company.
📚 This article has been professionally reviewed based on the following legal documents: