


Long Phan Consulting supports enterprises with LLC branch termination procedures in Vietnam, helping them stay fully compliant with current law and avoid tax code suspension or penalties for late notification. This is a two-stage procedure: the enterprise must first complete its tax obligations with the tax authority directly managing the branch, then file the termination dossier with the provincial Business Registration Authority. This article sets out the conditions, dossiers, procedures, and penalty levels under the Law on Enterprises and Businesses currently in effect, and Long Phan Consulting stands ready to assist enterprises throughout the process.

Important Legal Notes:
Terminating branch operations is only valid when the decision is made by the properly authorized person and the branch has fully settled its tax obligations before the business registration dossier is filed. Under Article 213 of the Law on Enterprises 2020, as amended by Clause 24, Article 1 of Law No. 76/2025/QH15 (effective from July 1, 2025), a branch terminates operations either by the enterprise’s own decision or by a decision of the competent state authority revoking the Branch Operation Registration Certificate.
For a one-member LLC, the Company Owner decides on branch termination, and this decision is documented as a Decision of the Owner. For a multi-member LLC, the authority belongs to the Members’ Council, and the enterprise must have a Resolution or Decision of the Members’ Council together with Minutes of Meeting evidencing the vote. The enterprise’s legal representative signs the notification sent to the Business Registration Authority, and if another person is authorized to file the dossier, a valid power of attorney is required.
Under Clause 1, Article 66 of Decree No. 168/2025/ND-CP on enterprise registration, before registering branch termination, the enterprise and branch must register with the tax authority to complete tax payment obligations under tax administration law. Clause 2, Article 66 of this Decree further sets a 10-day deadline, running from the decision date, to send the dossier to the provincial Business Registration Authority where the branch is located. These two deadlines are linked: the Business Registration Authority will not accept the branch termination dossier until the enterprise has confirmation of completed tax obligations from the tax authority directly managing the branch.
The enterprise must prepare two separate dossiers filed with two different authorities; the dossiers cannot be combined into one. These are the dossier filed with the tax authority and the dossier filed with the Business Registration Authority.
The dossier includes a request for termination of the tax code using Form No. 24/DK-TCT issued together with Circular No. 90/2026/TT-BTC (replacing Circular 86/2024/TT-BTC), along with documents evidencing completed tax obligations, such as tax finalization records or confirmation of no outstanding tax debt if requested by the tax authority. Where the branch has previously engaged in import-export activities, the enterprise must also submit a request for confirmation of completed import-export tax obligations to the customs authority. This dossier is filed with the tax authority directly managing the branch within 10 working days from the date of the branch termination decision.
Under Clause 3, Article 66 of Decree No. 168/2025/ND-CP, the branch termination registration dossier includes the following documents.

The LLC branch termination procedure follows a mandatory three-step sequence: settling tax obligations first, filing the business registration dossier second, and finally the state authority updating and publishing the information. The enterprise may not reverse this order.
Step 1: Complete tax obligations and terminate the branch’s tax code. Within 10 working days from the branch termination decision, the enterprise files a request to terminate the tax code with the tax authority directly managing the branch. The tax authority examines and reconciles any outstanding tax obligations, then issues a notice confirming tax code termination. This notice is a mandatory basis for proceeding to the next step.
Step 2: File the termination registration dossier with the provincial Business Registration Office. After obtaining confirmation of completed tax obligations, the enterprise files the branch termination registration dossier with the provincial Business Registration Authority where the branch is located. Under Article 20 of Decree 168/2025/ND-CP, this authority is now a specialized unit under the provincial or municipal Department of Finance, no longer under the Department of Planning and Investment as before July 1, 2025. Under Clause 2, Article 66 of Decree 168/2025/ND-CP, the filing deadline is 10 days from the termination decision. Enterprises should handle the tax procedure in parallel from the outset to avoid exceeding this common deadline.
Step 3: The Business Registration Authority updates legal status and publishes information. Within 3 working days of receiving a complete and valid dossier, the authority updates the branch’s legal status on the National Business Registration Database. It then sends the enterprise a confirmation notice of branch termination. If the dossier is invalid, the authority issues a written notice requesting amendment or supplementation.
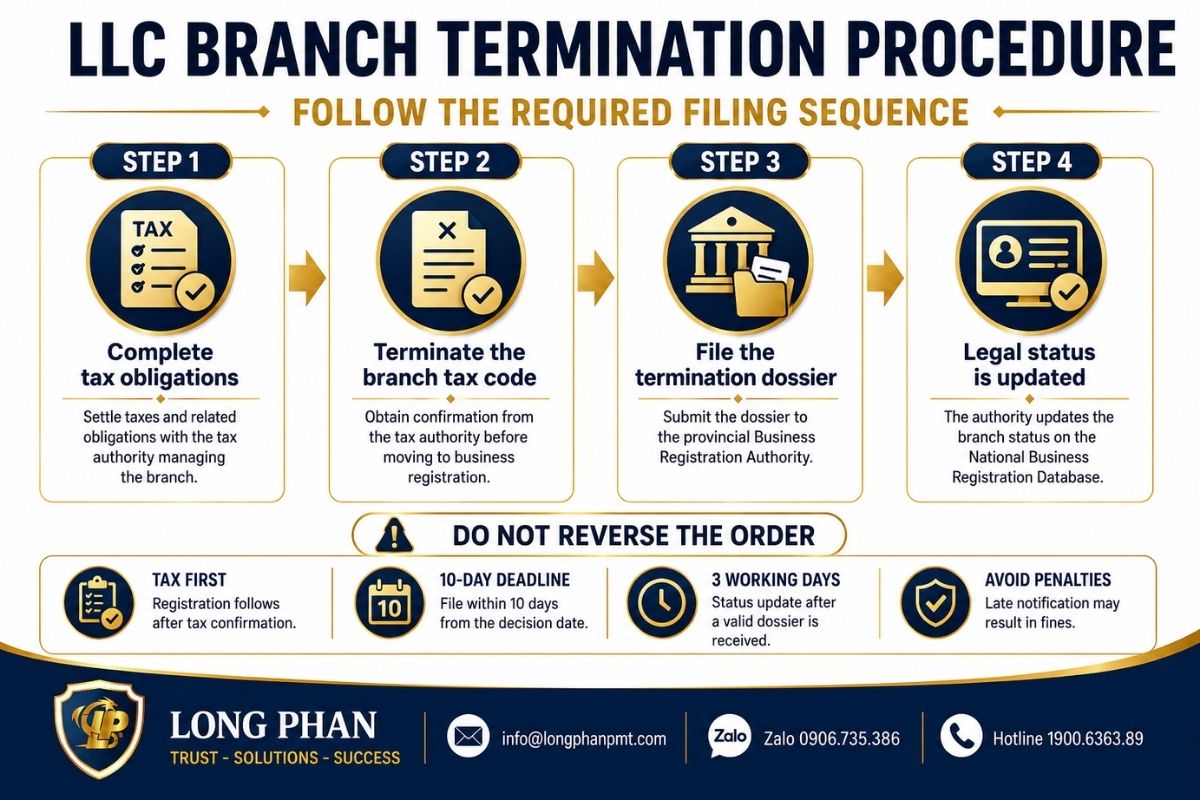
Both LLC types follow the same procedure and the same deadlines under Article 66 of Decree 168/2025/ND-CP, differing only in the internal document evidencing decision-making authority. The table below compares each criterion together with its applicable legal basis.
| Criteria | One-Member LLC | Multi-Member LLC | Legal Basis |
| Person/body with decision-making authority | Company Owner | Members’ Council | Article 213, Law on Enterprises 2020 (amended by Clause 24, Article 1, Law No. 76/2025/QH15); Point b, Clause 3, Article 66, Decree 168/2025/ND-CP |
| Required internal document | Decision of the Owner on branch termination | Resolution/Decision of the Members’ Council together with Minutes of Meeting | Point b, Clause 3, Article 66, Decree 168/2025/ND-CP |
| Notification of branch termination | Form No. 28, Appendix I, Circular 68/2025/TT-BTC | Form No. 28, Appendix I, Circular 68/2025/TT-BTC | Point a, Clause 3, Article 66, Decree 168/2025/ND-CP |
| Tax dossier (Form 24/DK-TCT) | Identical, regardless of LLC type | Identical, regardless of LLC type | Form No. 24/DK-TCT issued together with Article 36, Circular 90/2026/TT-BTC |
| Authority receiving the business registration dossier | Provincial Business Registration Authority where the branch is located (under the Department of Finance) | Provincial Business Registration Authority where the branch is located (under the Department of Finance) | Article 20 and Clause 2, Article 66, Decree 168/2025/ND-CP |
| Filing deadline | 10 days from the date of the decision | 10 days from the date of the decision | Clause 2, Article 66, Decree 168/2025/ND-CP |
A branch that has stopped operating in practice but has not been properly notified to the Business Registration Authority is still considered legally existing. The enterprise continues to bear reporting obligations, faces exposure to penalties, and may encounter obstacles in other procedures of the parent company, such as dissolution or business registration changes.
Under Point b, Clause 1, Article 54 of Decree No. 122/2021/ND-CP on administrative penalties in the planning and investment sector, terminating branch operations without notifying the Business Registration Authority is subject to a fine of VND 20,000,000 to VND 30,000,000 for organizations. Under Clause 2, Article 4 of this Decree, the fine for individuals equals half the fine applicable to organizations, that is, VND 10,000,000 to VND 15,000,000.
Under Clause 2, Article 54 of Decree No. 122/2021/ND-CP, in addition to the fine, the enterprise is subject to a remedial measure requiring it to notify the Business Registration Authority of the branch termination. The statute of limitations for administrative penalties in enterprise registration is 1 year from the time the violation ceased.
Long Phan Consulting provides end-to-end services for LLC branch termination procedures, including:
Enterprises seeking a preliminary assessment may send their documents via email at info@longphanpmt.com or Zalo/WhatsApp at +84 906 735 386.
Can a branch terminate operations before its tax finalization is complete? No. Under Clause 1, Article 66 of Decree 168/2025/ND-CP, the enterprise must complete its tax obligations and obtain the tax authority’s confirmation before the Business Registration Authority will accept the dossier.
No. Under Clause 1, Article 66 of Decree No. 168/2025/ND-CP, the enterprise must complete its tax obligations and obtain confirmation from the tax authority on the termination of the tax identification number before the Business Registration Authority accepts the application for termination of the branch’s operations.
No. Since a single-member limited liability company has only one owner, the application dossier only requires the Decision of the company owner under Clause 3, Article 66 of Decree No. 168/2025/ND-CP. Minutes of a Members’ Council meeting are not required, unlike in a multi-member limited liability company.
The application must be submitted to the provincial-level Business Registration Authority where the branch is headquartered. Under Article 20 of Decree No. 168/2025/ND-CP, this authority is currently a specialized unit under the Department of Finance and is no longer under the Department of Planning and Investment as it was before July 1, 2025.
Under Point b, Clause 1, Article 54 of Decree No. 122/2021/ND-CP, organizations may be fined from VND 20,000,000 to VND 30,000,000, while individuals may be fined from VND 10,000,000 to VND 15,000,000. In addition, Clause 2, Article 54 provides a remedial measure requiring the relevant notification to be submitted to the Business Registration Authority.
No. Termination of a branch’s operations and dissolution of the parent company are separate procedures under Article 213 of the Law on Enterprises 2020. The parent company may continue its normal operations after terminating one or more branches, unless it simultaneously carries out procedures for dissolution of the entire enterprise.
The Business Registration Authority processes the application within 3 working days from the date it receives a complete and valid dossier. However, the actual overall processing time depends on how long the tax authority takes to confirm completion of the branch’s tax obligations. The process may take longer if there are outstanding tax filings, invoices, or social insurance matters that have not yet been fully resolved.
Terminating LLC branch operations requires following the mandatory sequence: settling tax obligations first, then filing the business registration dossier. Both steps must fall within the strict 10-day deadline from the decision date to avoid fines of up to VND 30 million. Long Phan Consulting accompanies enterprises through this entire process, from preparing internal documents to working with the tax authority and the Business Registration Authority. Contact hotline 1900636389 for timely support.
📚 This article has been professionally reviewed based on the following legal documents:


