


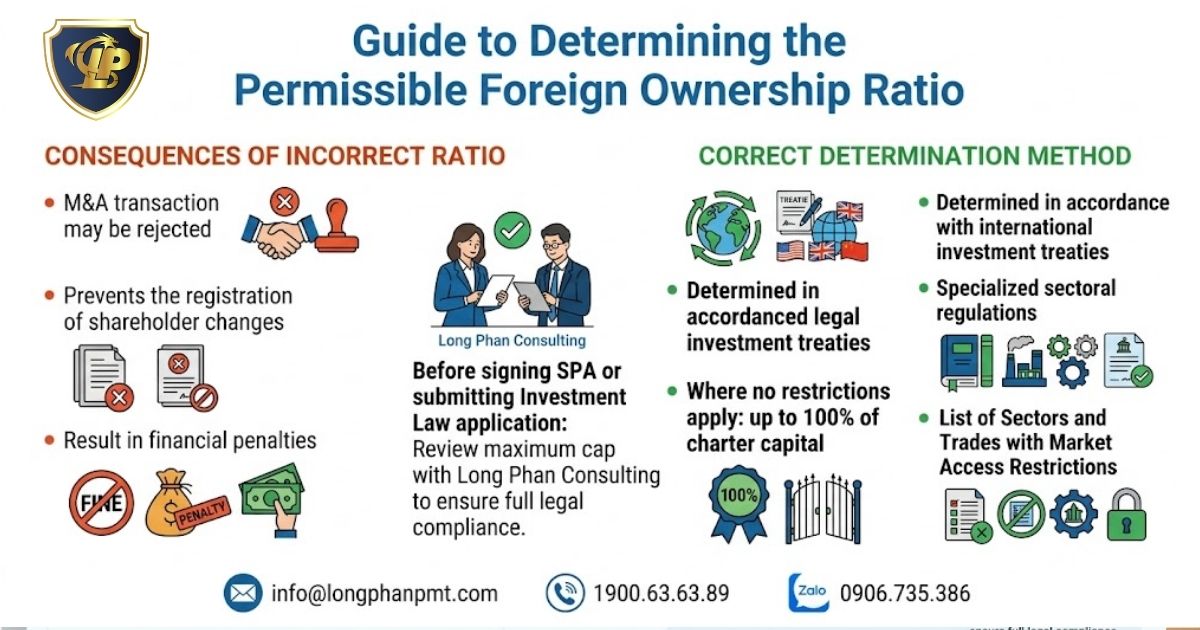
An inaccurate foreign ownership ratio may lead to rejection of an M&A deal, delays in registering shareholder changes, or administrative sanctions. Under the Law on Investment, the permitted foreign shareholding level must be assessed against international investment commitments, sector-specific regulations, and the market access negative list. Where no ownership restriction applies, foreign investors may hold up to 100% of the charter capital. Before executing a Share Purchase Agreement or filing transaction documents, foreign-invested enterprises should verify the applicable ownership ceiling with Long Phan Consulting to protect transaction validity and avoid compliance risks.
Key legal notes:
The Foreign Ownership Limit is not determined by an investor’s desired level of corporate control. Valid limits must derive from Market Access Conditions, the actual business lines, and the reservation mechanisms of investment laws.
Foreign Investors are granted market access identical to domestic investors, except for sectors listed in the negative list. Long Phan Consulting Company supports enterprises in verifying these foundational principles to define the maximum foreign equity cap, pursuant to Clause 1, Article 8 of the Law on Investment 2025.
Our compliance checks for market access include:
We ensure diversified businesses do not mistakenly apply a 100% cap to conditional sectors.
The investment condition reservation mechanism protects investors with valid approvals before market policies shifted. Long Phan Consulting Company assists Foreign-invested Economic Organizations in maintaining favorable conditions per their existing Investment Registration Certificate (IRC), pursuant to Clause 9, Article 52 of Law on Investment 2025.
Critical transition rules managed by our legal team:
We mitigate the risk of adjustment dossier rejections during subsequent expansion deals.
In M&A Transactions, misidentifying these principles can stall the entire process of signing, payment, and updating shareholder registers. Long Phan Consulting Company provides comprehensive legal audits to review the statutory basis before clients negotiate equity stakes or voting rights.
Our advisory scope covers:
This strategic audit secures the transaction flow and prevents forced equity restructurings.
Cross-border M&A Transactions require stringent equity appraisals prior to executing a Share Purchase Agreement (SPA), disbursing funds, or submitting shareholder update dossiers. Misclassifying a single sector or overlooking specialized conditions can invalidate the entire ownership cap. The following procedure assists Foreign Investors and target enterprises in determining the statutory foreign charter capital ratio, rather than relying strictly on desired commercial equity.
The initial phase demands identifying the actual business lines of the target enterprise. This establishes whether the transaction falls under conditional market access sectors.
Compliance risks frequently emerge when target enterprises register broad sectors while conducting restricted core activities. Investment Registration Authorities assess the actual operational nature during M&A appraisals.
Following sector identification, Foreign Investors must audit international investment treaties to which Vietnam is a signatory. This determines the market openness level, investment forms, and the maximum foreign ownership limit.
Auditing international commitments prevents the false assumption of universal 100% equity allowances. Discrepancies between VSIC and CPC classifications can fundamentally alter legal conclusions for service sectors.
The negative list for market access serves as a mandatory compliance filter before finalizing foreign equity caps. Enterprises must clearly distinguish between prohibited and conditional market access sectors.
This assessment is critical for multi-sector Enterprises. A single restricted secondary business line creates a bottleneck, significantly reducing the allowable ownership for the entire transaction.
Specialized laws impose independent ownership ceilings overriding general investment regulations. This secondary compliance check is mandatory for finance, telecommunications, aviation, journalism, education, logistics, and real estate sectors.
Commercial control in banking, securities, or aviation is inseparable from licensing conditions. Exceeding specialized caps leads to transaction rejections despite mutual pricing and transfer agreements.
Upon completing the four-tier audit, Enterprises possess the legal foundation to define the final foreign ownership limit. This definitive threshold must withstand scrutiny from investment registrars and specialized regulatory authorities.
The concluded equity appraisal establishes more than a capital figure. It provides the architectural blueprint for the SPA, condition precedents, payment schedules, and application strategies at the Department of Planning and Investment (DPI).
Specialized business sectors require more than the general Investment Law to determine the foreign ownership limit. Foreign Investors must concurrently evaluate international treaties, the list of sectors with market access restrictions, and specialized legislation. For finance, infrastructure, transport, education, or real estate, foreign equity ratios tie directly to operational conditions. Incorrect caps can immediately halt M&A Transactions during the dossier appraisal phase.
| Business Sector | Applicable Specialized Legislation | Maximum Ownership Limit |
| Banking | Law on Credit Institutions 2024 and related specialized regulations | Subject to credit institution limits; special cases require approved plans. |
| Securities | Specialized securities laws and Section B, Appendix I of Decree 96/2026/ND-CP | Determined by Market Access Conditions, specialized laws, and specific corporate structures. |
| Telecommunications | Specialized telecom laws and Section B, Appendix I of Decree 96/2026/ND-CP | Determined by service scope, network infrastructure, and Market Access Conditions. |
| Aviation | Specialized aviation laws and Section B, Appendix I of Decree 96/2026/ND-CP | Determined by transport type, operational conditions, and specialized statutory limits. |
| Logistics | International commitments, specialized laws, and Section B, Appendix I of Decree 96/2026/ND-CP | Determined per specific logistics service; no universal industry cap applies. |
| Education | Specialized education laws and conditional market access mechanisms | Determined by facility type, program, educational level, and specific investment conditions. |
| Real Estate | Specialized real estate and land laws, plus Market Access Conditions | Determined by project type, land use rights, and permitted business scope. |
This table serves as an appraisal framework. Final caps demand specific dossier validation, especially when Enterprises operate across multiple sectors or hold land use rights in sensitive geographic areas.
Banking and securities face strict legal oversight due to systemic financial safety, governance rights, and capital market transparency. Foreign Investors must assess shareholder conditions, financial capacity, and control structures beyond mere equity percentages.
For credit institutions, ownership ratios must strictly comply with the Law on Credit Institutions 2024. If investors acquire all shares of a specially controlled credit institution, ownership may exceed standard limits per an approved restructuring plan. However, a roadmap to reduce the ownership ratio is mandatory, pursuant to Clause 2, Article 176 of the Law on Credit Institutions 2024.
For securities, the foreign ownership cap depends on specialized laws, Market Access Conditions, and the public or listed status of the company. A critical risk involves confusing economic ownership with legal control rights. Commercially viable capital ratios will face rejection if specialized conditions are violated.
Telecommunications, aviation, and logistics are subject to both Market Access Conditions and unique operational requirements. The ownership ceiling fluctuates based on service scope, infrastructure, licenses, and relevant international commitments.
These fall under conditional market access sectors for foreign investors, pursuant to Section B, Appendix I of Decree 96/2026/ND-CP. Foreign Investors must verify equity limits, investment forms, and operational conditions before finalizing the deal structure.
For logistics, the maximum foreign ownership lacks a universal percentage. Individual logistics services face distinct market opening commitments and operational prerequisites.
For telecommunications and aviation, regulatory authorities heavily scrutinize infrastructure, specialized licenses, national security, and operational control. Enterprises must concurrently review sector dossiers, specialized licenses, and capital transfer plans to ensure total compliance.
Education and real estate are highly sensitive sectors intrinsically tied to operational conditions, locations, projects, and land use rights. Foreign Investors must align capital ratios with operational models, specialized licenses, and permitted business scopes.
In education, capital structures must adhere to the facility type, training program, educational level, and applicable investment conditions. EdTech startups face significant risks if authorities reclassify their technology models as conditional educational services.
In real estate, ownership ratios necessitate concurrent assessments of land use rights, project types, and permitted scopes. If the target enterprise holds land use rights on islands, border communes, coastal areas, or zones affecting national defense, the transaction must satisfy strict defense, security, and land conditions, pursuant to Clause 2, Article 21 of the Law on Investment 2025.
These sectors demand rigorous legal due diligence before signing a Share Purchase Agreement (SPA). Seemingly valid equity ratios are routinely blocked if business lines, licenses, or project land remain incompatible with foreign investment.
After determining the maximum foreign ownership ratio, Foreign Investors must translate this appraisal into the transaction dossier. This determines whether state authorities will legally recognize the new ownership structure. Severe risks arise when parties sign the Share Purchase Agreement (SPA) before verifying registration conditions. Commercial payments may finalize without legal recognition of ownership.
Capital contribution and share purchase transactions require preemptive reviews if the target enterprise operates in conditional market access sectors. The dossier must be submitted to the Investment Registration Authority where the economic organization is headquartered, pursuant to Clause 3, Article 76 of Decree 96/2026/ND-CP.
Registration compliance requires the following steps:
Dossier structures must strictly reflect the transaction nature. Initial share purchases, acquisitions of local firms, or partial capital buyouts pose distinct risks regarding corporate control and market access.
Appraisal timelines critically impact M&A closing schedules. The Investment Registration Authority assesses the conditions and notifies investors within 10 working days upon receiving a valid dossier, pursuant to Clause 4, Article 76 of Decree 96/2026/ND-CP.
A national defense and security appraisal is triggered if the target enterprise holds land use rights in sensitive geographic areas. Investors must ensure national security compliance for land on islands, border communes, or coastal areas, pursuant to Clause 2, Article 21 of the Law on Investment 2025.
Strategic management of the appraisal process involves:
The 02-day consultation dispatch deadline applies pursuant to Point a, Clause 5, Article 76 of Decree 96/2026/ND-CP. Overlooking land elements can severely delay the closing schedule beyond financial projections.
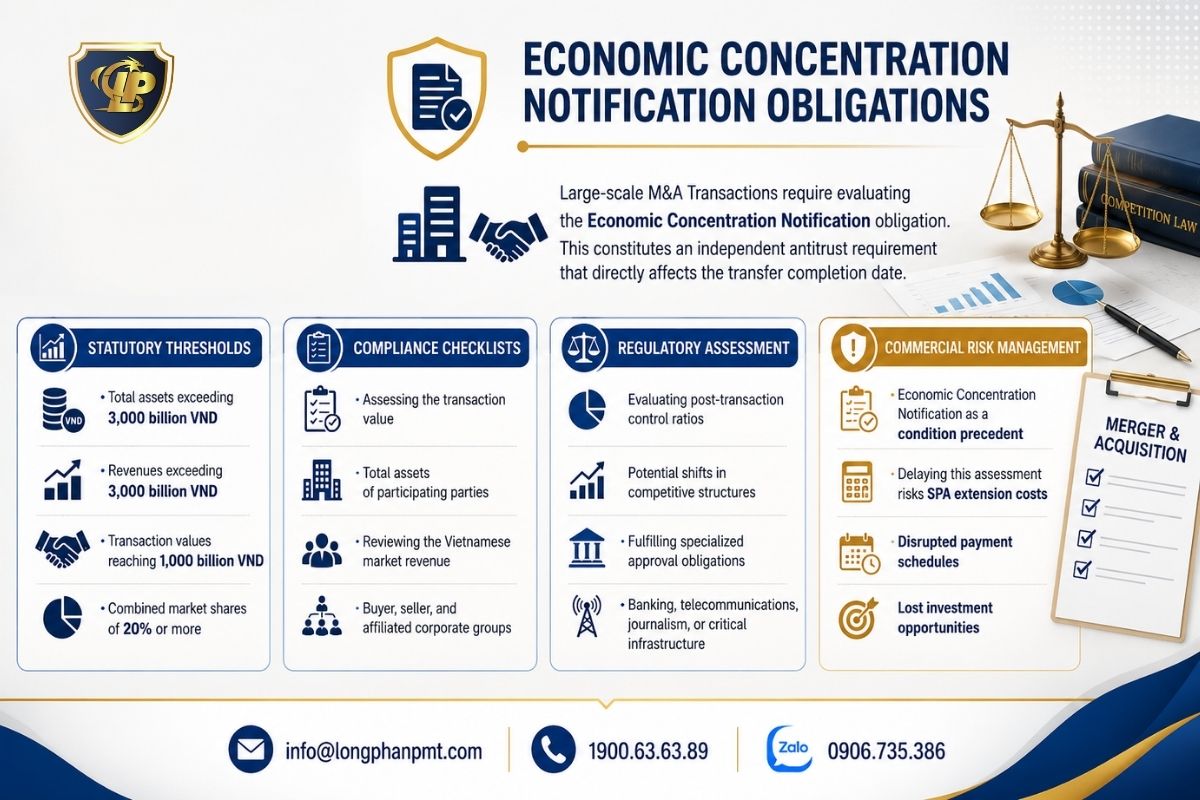
Beyond capital registration, large-scale M&A Transactions require evaluating the Economic Concentration Notification obligation. This constitutes an independent antitrust requirement that directly affects the transfer completion date. Statutory thresholds involve total assets or revenues in Vietnam exceeding 3,000 billion VND, transaction values reaching 1,000 billion VND, or combined market shares of 20% or more.
Enterprises must implement strict compliance checklists before issuing shares or executing the SPA:
Commercially, the Economic Concentration Notification must be structured as a condition precedent. Delaying this assessment risks SPA extension costs, disrupted payment schedules, and lost investment opportunities.
Violating Market Access Conditions exceeds mere administrative errors in investment dossiers. In M&A Transactions, this risk delays closing schedules, breaches payment terms, and strips Foreign Investors of intended control. Enterprises must evaluate risks across two tiers: transaction validity and state regulatory penalties. Exceeding statutory equity caps can trigger dossier rejections, financial fines, mandatory remedial measures, or outright project termination.
The most critical risk occurs when a transaction is executed commercially but denied legal recognition. If the foreign ownership limit is breached, competent authorities will refuse to record shareholder changes or update corporate registration documents.
Common regulatory deadlocks include:
For sham transactions, the Investment Registration Authority can terminate the project wholly or partially upon a Court or arbitral ruling, pursuant to Clause 1, Article 68 of Decree 96/2026/ND-CP. Commercially, the Share Purchase Agreement (SPA) must condition the ownership ratio upon statutory investment approvals to protect buyers from disbursing funds without acquiring voting rights or profit repatriation capacities.
Administrative penalties must be factored as mandatory risk costs during M&A due diligence. Beyond financial fines, enterprises face forced operational termination, disgorgement of illegal profits, or mandatory ownership restructuring.
| Violation | Penalty and Consequence | Legal Basis |
| Failing to meet conditions for capital contribution and share purchases | 80,000,000 VND to 100,000,000 VND | Clause 1, Article 16 of Decree 122/2021/ND-CP |
| Foreign Investors or FIEs receiving project transfers without meeting conditions | 100,000,000 VND to 200,000,000 VND | Point b, Clause 2, Article 16 of Decree 122/2021/ND-CP |
| Conducting business operations in prohibited investment sectors | 200,000,000 VND to 300,000,000 VND, plus mandatory termination and disgorgement of illegal profits | Clauses 3 and 4, Article 16 of Decree 122/2021/ND-CP |
| Falsifying or inaccurately declaring dossiers to obtain investment approvals | 70,000,000 VND to 100,000,000 VND | Clause 2, Article 17 of Decree 122/2021/ND-CP |
This penalty framework proves that risks extend far beyond monetary fines. For transactions governed by disbursement schedules, an administrative sanction can trigger contract breaches or compensation liabilities. Foreign Investors must demand rigorous equity appraisals prior to executing formal transfer clauses.
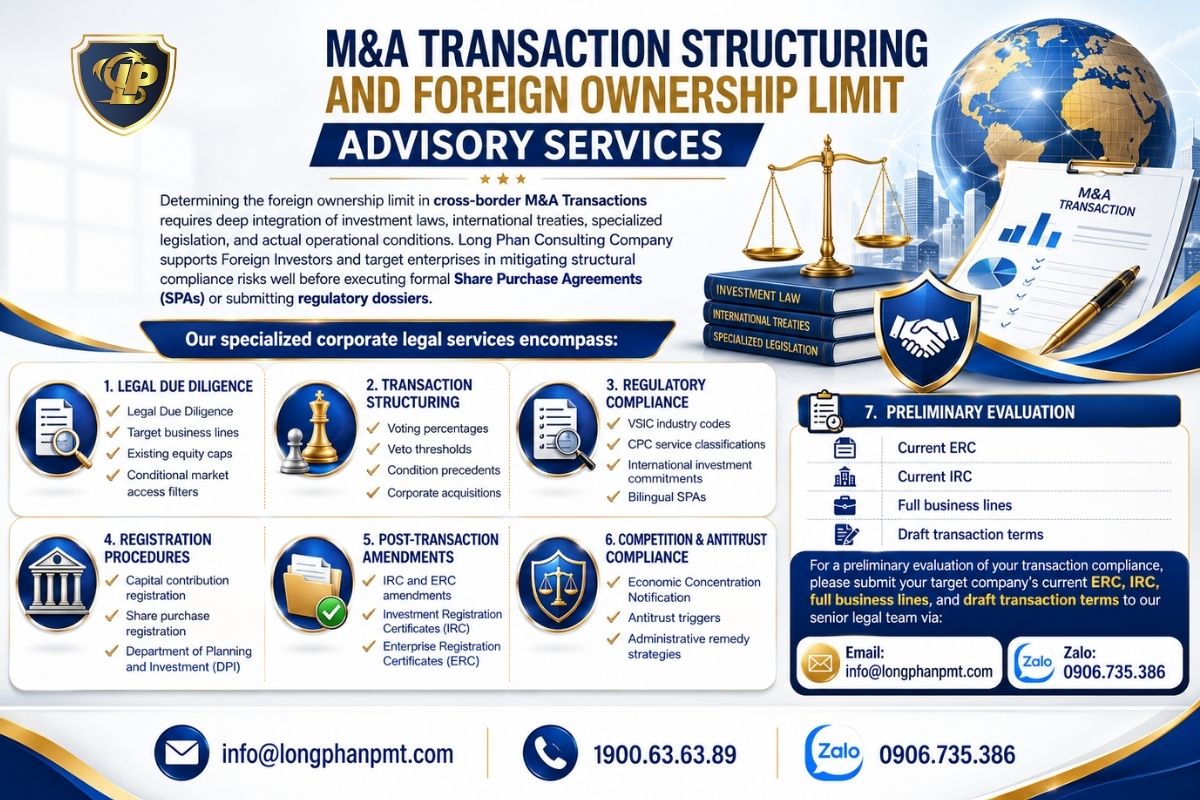
Determining the foreign ownership limit in cross-border M&A Transactions requires deep integration of investment laws, international treaties, specialized legislation, and actual operational conditions. Long Phan Consulting Company supports Foreign Investors and target enterprises in mitigating structural compliance risks well before executing formal Share Purchase Agreements (SPAs) or submitting regulatory dossiers.
Our specialized corporate legal services encompass:
For a preliminary evaluation of your transaction compliance, please submit your target company’s current ERC, IRC, full business lines, and draft transaction terms to our senior legal team via Email: info@longphanpmt.com or Zalo: 0906.735.386.
The process of M&A negotiations and restructuring of international capital flows always carries inherent legal blind spots regarding “foreign ownership ratios.” Proactively identifying compliance risks helps investors establish absolutely secure transaction structures. The following in-depth Q&A content will directly address the most complex issues in business operations.
Foreign investors are fully permitted to own up to 100% of the charter capital, similar to domestic investors. The current legal framework clearly stipulates the mechanism to guarantee this right for sectors that are not restricted. Specifically, in cases where Vietnamese law does not restrict market access for sectors that have not been committed to, foreign investors have market access as stipulated for domestic investors according to Point a, Clause 4, Article 17 of Decree No. 96/2026/ND-CP.
The target enterprise is required to apply the lowest foreign ownership limit among its business sectors. Investors cannot apply the highest limit to acquire shares. The legal principle stipulates that if the target enterprise operates in multiple sectors with different foreign ownership limits according to international treaties, the maximum foreign ownership ratio in that enterprise must not exceed the lowest limit among its business sectors as specified in Point d, Clause 10, Article 17 of Decree No. 96/2026/ND-CP.
The investment registration authority is responsible for reviewing and notifying the approval results within exactly 10 working days. This administrative procedure review process is calculated from the time the state agency receives a complete and valid application. The deadline for the investment registration authority to review whether the conditions for capital contribution, share purchase, or equity purchase are met and to notify the investor, from the date of receiving a valid application, is 10 working days, as stipulated in Clause 4, Article 76 of Decree No. 96/2026/ND-CP.
The practice of using nominees to register assets carries the risk of the state agency terminating the entire project and revoking the investment status. Establishing this fictitious ownership structure seriously violates market access conditions. The investment registration authority has the right to terminate a project if the investor conducts investment activities based on fraudulent civil transactions, as determined by a court or arbitration tribunal, in accordance with Clause 1, Article 68 of Decree No. 96/2026/ND-CP.
Businesses that violate the regulations will be subject to high cash fines and required to return all illegal profits. This strict penalty framework is applied to protect key sectors. Fines ranging from VND 200,000,000 to VND 300,000,000 apply to the act of conducting investment and business activities in prohibited sectors, and the business will be forced to cease operations as stipulated in Clauses 3 and 4 of Article 16 of Decree No. 122/2021/ND-CP.
Economic organizations are required to undergo a verification process involving two provincial-level agencies before their applications are approved. The investment registration agency will be the focal point for sending these verification documents. The deadline for the investment registration agency to send the verification documents to the Provincial Military Command and the Provincial Police Department for economic organizations with land use right certificates in areas affecting national defense and security is two working days, as stipulated in Point a, Clause 5, Article 76 of Decree No. 96/2026/ND-CP.
Accurately calculating the statutory Foreign Ownership Limit in Vietnam remains the foundational prerequisite for Foreign Investors and Foreign-invested Economic Organizations to finalize M&A Transactions, execute capital contributions, or register share purchases without incurring regulatory gridlocks. Enterprises must conduct multi-tiered legal audits covering business lines, international treaties, negative lists for market access, and specialized laws prior to executing an SPA or disbursing capital. Miscalculating these sectoral caps directly exposes transactions to dossier rejections, financial sanctions, and the loss of operational control. Contact the corporate legal experts at Long Phan Consulting Company via our Hotline: 1900636389 to secure your market entry and structure fully compliant cross-border transactions.
📚 This article is provided with professional consultation based on the following legal framework:


