Performing invoice cancellation for dissolved or bankrupt enterprises is a critical step in terminating business operations according to legal regulations. Correctly executing invoice cancellation procedures helps enterprises complete tax obligations, avoid legal risks, and ensure financial transparency. It also serves as a basis for tax authorities to control and prevent the misuse of invoices after the enterprise has ceased operations.

Dissolution under Article 207 of the Law on Enterprises 2020 or bankruptcy under Article 59 of the Law on Bankruptcy 2014 leads to the termination of the business entity. At this point, the enterprise must liquidate assets and fulfill obligations to state management agencies, including handling unused invoices. The invoice cancellation for dissolved or bankrupt enterprises is an inseparable step in the tax code closure process.
Pursuant to Article 39 of the Law on Tax Administration 2019, taxpayers must complete tax filing, tax payment, and invoice handling before the tax code termination. Enterprises must destroy printed invoices purchased from tax authorities or self-printed invoices that have been issued but unused. This measure prevents the issuance of fraudulent invoices or illegal invoice usage after operations have ceased.
According to Article 25 of Decree 123/2020/ND-CP (amended by Clause 3, Article 2 of Decree 70/2025/ND-CP), enterprises approved to cease tax code usage must stop using unused invoices. The direct managing tax authority has the right to announce the expiration of these invoices if the enterprise fails to do so voluntarily.
>>>See more at: Certificate of Origin Form D Issuance
Based on Clause 1, Article 27 of Decree 123/2020/ND-CP, enterprises with unused invoices must destroy them no later than 30 days from the date of notifying the tax authority. In voluntary dissolution, enterprises should proactively review inventory and conduct this parallel to submitting dissolution files. Extending beyond 30 days leads to administrative penalties.
If the tax authority announces invoices have expired, the enterprise must destroy them no later than 10 days from the announcement date or the date lost invoices are recovered.
For bankruptcy, the asset management officer or enterprise managing liquidation must closely monitor this timeline to ensure compliance with Bankruptcy and Tax laws.
According to Point d, Clause 2, Article 27 of Decree 123/2020/ND-CP (amended by Clause 3, Article 2 of Decree 70/2025/ND-CP), the dossier includes:
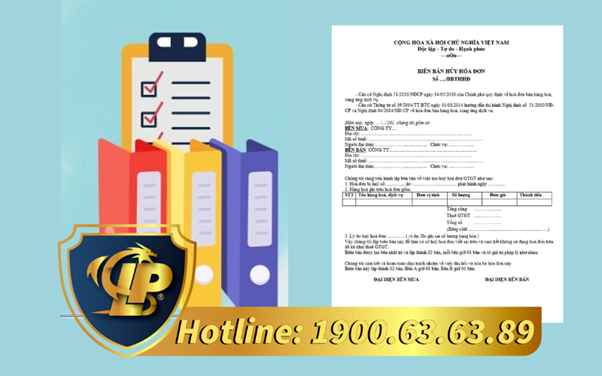
The procedure for invoice cancellation for dissolved or bankrupt enterprises follows these steps:
Step 1: Inventory and Council Formation The accounting department reviews all unused invoices (printed and electronic). The enterprise establishes an Invoice Cancellation Council, which must include a leadership representative and an accounting representative (Point b, Clause 2, Article 27, Decree 123/2020/ND-CP amended by Decree 70/2025/ND-CP).
Step 2: Execution of Cancellation
Enterprises must notify the managing agency after physical destruction. Sending the Notice of Invoice Cancellation Results is the final step to confirm the legal status of cancelled invoices.
According to Clause 2, Article 27 of Decree 123/2020/ND-CP (amended by Decree 70/2025/ND-CP), the Notice (Form 02/HUY-HDG) is made in 02 copies (one stored, one sent). The deadline for sending constitutes no more than 05 days from the cancellation date.
The notice must detail invoice identifiers, quantity, reason (dissolution/bankruptcy), date/time, and method. Submission can be via the General Department of Taxation’s portal (Thuedientu) or T-VAN providers. This completes a key part of the tax code closure obligation under Article 39 of the Law on Tax Administration 2019.
>>> See more at: What documents are required to announce dissolution of a joint stock company?
Long Phan Consulting Company supports enterprises in completing dissolution procedures quickly and legally. Our services include:
>>> See more at: Closing the Tax ID Number for Foreign Investors
FFrom the cancellation date. Late submission incurs administrative penalties. (Legal Basis: Clause 2, Article 27, Decree 123/2020/ND-CP amended by Decree 70/2025/ND-CP).
No. Business households and individuals are exempt from establishing an Invoice Cancellation Council but must still perform inventory, destruction, and submit the Notice on time. (Legal Basis: Point d, Clause 2, Article 27, Decree 123/2020/ND-CP amended by Decree 70/2025/ND-CP).
The dossier (Decision, Inventory, Minutes, Notice) must be stored according to accounting laws (typically 10 years). The legal representative or authorized archive organization is responsible. (Legal Basis: Point d, Clause 2, Article 27, Decree 123/2020/ND-CP amended by Decree 70/2025/ND-CP).
Methods include cutting corners, shredding, or burning, ensuring the invoice cannot be restored to its original form/content. (Legal Basis: Point c, Clause 2, Article 27, Decree 123/2020/ND-CP amended by Decree 70/2025/ND-CP).
Cancellation occurs after the dissolution decision and cessation of revenue-generating activities, but before submitting the final tax code closure dossier. (Legal Basis: Article 39, Law on Tax Administration 2019).
>>>See more at: Permit for Transporting Dangerous Goods by Road
Compliance with invoice cancellation for dissolved or bankrupt enterprises ensures legal tax code closure. Clients must observe timelines and dossier requirements to avoid risks. For in-depth support on dissolution and invoice handling, please contact Long Phan Consulting Company via Hotline 1900.63.63.89.