
Law on Enterprises and Businesses: A capital restructuring strategy for obtaining real estate credit must now comply closely with the 2023–2024 legal framework, as collateral alone is no longer sufficient to secure loan approval. Foreign developers may face immediate refusal if they fail to satisfy the new minimum equity ratio of 15% to 20% of total investment capital or miss the compulsory 90-day capital contribution deadline. These stricter credit controls and the move toward digital tax compliance require a proactive advisory partner to review financial structures before bank submission.
Through charter capital restructuring, SPV-based risk segregation, or partial project transfers, investors can reduce compliance exposure and preserve liquidity with strategic guidance from Long Phan Consulting Company.
Important legal note:
Restructuring capital for real estate credit is more than just adjusting debt ratios; it is a strategic optimization of financial capacity to satisfy rigorous banking standards. Under the 2023 Law on Real Estate Business, new technical barriers and strict minimum equity thresholds require developers to consolidate their capital structures from the outset to ensure the legal feasibility of their projects.
When seeking credit, developers cannot rely solely on “secured assets.” Banks now prioritize an audit of core financial capacity, specifically the ratio of equity capital to total project investment.
| Project Scale | Minimum Equity Ratio | Significance for Credit Appraisal |
| Land use scale under 20 hectares | Not lower than 20% of total investment | Mandatory legal entry threshold before a loan is considered. |
| Land use scale of 20 hectares or more | Not lower than 15% of total investment | Demonstrates minimum financial capacity for large-scale projects. |
| Developers managing multiple simultaneous projects | Must allocate sufficient capital per project | One capital sum cannot be used to prove capacity for multiple projects. |
Pursuant to Point c, Clause 2, Article 9 of the 2023 Law on Real Estate Business, these 20% or 15% ratios are mandatory conditions. Failure to meet these thresholds signals a lack of implementation capacity, leading to loan rejection. Strategic solutions include increasing actually contributed capital, converting shareholder loans into equity, or onboarding strategic investors into the project’s legal entity.
Credit “room” for real estate is under pressure as lending limits tighten. Relying on a single bank poses a significant risk of mid-term funding shortages.
For large-scale developments, investors should prepare syndicated loan options, phased disbursement schedules, and supplemental equity sources to prevent bottlenecks when banks hit their safety limits.
In modern financial management, establishing a comprehensive audit strategy is more than just verifying figures; it is a vital link in standardizing the equity structure. This process allows enterprises to accurately identify the status of actually contributed charter capital and proactively resolve potential liabilities, creating a transparent financial foundation for sustainable project development.
Capital structure auditing aims to prove that equity is authentic, cash flow sources are transparent, and liabilities are not concealed from the bank. Investors must review items that directly impact repayment capacity and equity ratios:
Pursuant to Clause 5, Article 16 of the 2020 Law on Enterprises, declaring “ghost” charter capital or failing to contribute capital as registered is strictly prohibited. Consequently, capital increases only hold credit value when backed by legitimate cash flows and valid documentation.
A common mistake is using the same equity sum to prove financial capacity for multiple projects simultaneously. Banks will likely exclude this when assessing concurrent implementation capabilities.
Pursuant to Point c, Clause 2, Article 9 of the 2023 Law on Real Estate Business, developers must ensure that equity capital is sufficiently allocated to each specific project to maintain safety ratios across the entire portfolio. From a management perspective, developers should maintain an allocation ledger detailing utilized capital, committed capital, and valid supplementary sources for each project phase.
Creating a Special Purpose Vehicle (SPV) or project-specific legal entity helps isolate cash flow risks and clarify capital ownership. This is an ideal solution when a parent company manages diverse projects, carries existing debt, or intends to onboard strategic investors.
When establishing an SPV, the contribution records, charters, voting rights, and cash flow control mechanisms must be standardized. This structure should be designed in alignment with the 2020 Law on Enterprises to prevent conflicts between legal filings and credit profiles. Furthermore, if the entity plans to raise capital through public offerings, note that pursuant to Point a, Clause 3, Article 15 of the 2019 Law on Securities, a minimum contributed charter capital of 30 billion VND is required at the time of registration.
Establishing a project entity, or SPV, helps isolate cash flow risks and clarify ownership of capital. This is a suitable solution when the parent company has multiple projects, significant debts, or needs to attract strategic investors.
When establishing a Special Purpose Vehicle (SPV), businesses need to standardize the capital contribution documentation, charter, voting rights, share transfer, and cash flow control mechanism. This content should be designed in conjunction with the 2023 Enterprise Law to avoid conflicts between legal and credit documentation.
If a business plans to raise capital through a public offering of securities, the capital threshold is a factor that must be checked early. Businesses offering bonds to the public must have a paid-up charter capital of at least VND 30 billion at the time of registration, according to point a, clause 3, Article 15 of the 2019 Securities Law.
In project financing, restructuring collateral is a decisive factor in determining credit limits and loan security. This process demands absolute precision regarding the validity of legal dossiers, particularly satisfying prerequisites for mortgaging land use rights and property rights arising from the project to ensure payment priority and minimize future legal disputes.
Collateral only holds credit value when a bank can control ownership, usage rights, and the ability to liquidate the asset. Therefore, “pledging the project’s Red Book” must be standardized into a mortgage of land use rights, property rights arising from the project, or future-formed assets.
Investors must review the status of Land Use Right Certificates, investment policy approvals, 1/500 detailed planning, and construction permits. Pursuant to No.21/2021/NĐ-CP, collateral whether existing or future-formed must legally belong to the securing party. For projects already sold or lease-purchased, the obligation to issue certificates to customers affects asset security. Under Clause 3, Article 17 of the 2023 Law on Real Estate Business, developers must submit applications for customer certificates within 50 days of handover or full payment.
Revenue from customers is a factor scrutinized heavily by banks. If an enterprise collects money at the wrong time, exceeds permitted ratios, or lacks guarantees, project cash flow may be flagged as a legal risk. Before including projected revenue in a repayment plan, developers must standardize the following milestones:
If deposits or initial payments are recorded incorrectly, banks may exclude them from the repayment cash flow. Developers should separate project accounts and payment schedules to mitigate the risk of disbursement suspension.
In the process of optimizing financial structure, restructuring loan capital accompanied by a feasible debt repayment cash flow plan is a key factor in ensuring project liquidity. This requires businesses to have a rigorous view in defining legitimate loan purposes, separating essential capital needs from categories prohibited from disbursement according to current regulations of the State Bank of Vietnam, thereby building solid trust with credit institutions.
Optimizing a financial structure requires a viable repayment cash flow plan as a cornerstone for project liquidity. This demands that enterprises strictly differentiate between valid loan purposes and prohibited funding needs under current State Bank of Vietnam regulations, thereby building solid trust with credit institutions.

Real estate credit profiles must be designed according to legal capital usage purposes, not merely the developer’s immediate cash shortage. If a loan plan is perceived as “debt evergreening” (refinancing to hide bad debt), banks will likely refuse disbursement.
| Funding Need | Credit Risk | Potential Exception |
| Borrowing to pay debt at the same lending institution | Restricted capital use | May be permitted to pay interest arising during construction if such interest is included in the approved construction estimate. |
| Borrowing to pay debt at another credit institution | Requires proof of valid refinancing | Considered if the old loan served business activities and the new term does not exceed the remaining term of the old loan. |
| Supplemental working capital for a project | Scrutinized for repayment capacity | Requires clear documentation of sales revenue, leasing, transfers, or supplemental capital contributions. |
Pursuant to Clause 5, Article 8 of Circular 39/2016/TT-NHNN, enterprises are generally prohibited from borrowing to pay debts at the same lending institution. However, under Clause 6, Article 8 of the same Circular, refinancing a loan from another bank is possible if the debt has not been previously restructured and the new loan remains within the original term.
Refinancing is not a tool to hide non-performing loans; it is a mechanism to restructure capital sources by proving business purpose, collateral value, and repayment cash flow.
Developers must review all legacy credit contracts, especially indefinite-term agreements. Pursuant to Clause 2, Article 210 of the 2024 Law on Credit Institutions, existing indefinite-term credit agreements that conflict with the new law may only be maintained until June 30, 2025. To strengthen a credit profile, enterprises should prepare detailed repayment schedules and phased disbursement plans. The more transparent the cash flow documentation, the more likely the bank is to categorize the loan as a legitimate refinancing rather than a high-risk debt rollover.
In an environment of tightening credit and rising capital costs, implementing a partial project transfer acts as a strategic “thaw,” allowing developers to quickly restructure cash flow and alleviate financial burdens. Adhering to the legal framework for project transfers under Decree 96/2024/NĐ-CP is a prerequisite to ensure compatibility between business goals and rigorous regulatory standards.
Transferring all or part of a real estate project is more than just a capital recovery transaction; it is a debt restructuring tool that introduces new investors and reduces bank credit pressure.
| Project Approval Authority | Approving Body for Transfer | Significance for Capital Restructuring |
| Projects decided or approved by the Prime Minister | The Prime Minister | Suitable for large-scale projects with high impact on capital structure. |
| Projects decided or approved by Provincial People’s Committees | Provincial People’s Committee | Suitable for most local projects needing partial transfer to supplement cash flow. |
Pursuant to Points a and b, Clause 2, Article 41 of the 2023 Law on Real Estate Business, developers must identify the correct authority before negotiating with transferees. Decree 96/2024/NĐ-CP serves as the primary guidance for transfer procedures post-August 1, 2024. Enterprises should standardize their investment policy approvals, 1/500 planning, and land-related financial obligations. Once a transaction is completed, public system information must be updated within 05 working days, pursuant to Clause 5, Article 4 of Decree 96/2024/NĐ-CP.
Transitional rules may provide relief for projects under debt pressure or those submitted before the new laws took effect. However, these should not be viewed as a permanent exemption from compliance.
Existing real estate enterprises that do not yet meet the new legal requirements must complete their supplemental compliance within 06 months of the law’s effective date, as mandated by Clause 1, Article 83 of the 2023 Law on Real Estate Business.
In the process of restructuring capital, proactively identifying and establishing legal “checkpoints” is vital for the survival of a project. This is especially critical as state authorities tighten inspections and apply strict sanctions against “ghost” capital contributions or the misuse of deposits, ensuring transparency and the rule of law in the real estate sector.
Incorrect capital restructuring can cause a credit profile to be classified as high-risk. Banks routinely verify the authenticity of capital contributions, the source of customer funds, and the alignment between cash flow and project legalities. Developers must control actions that could misrepresent actual financial capacity:
Pursuant to Clause 5, Article 16 of the 2020 Law on Enterprises, declaring “ghost” capital or failing to contribute registered capital is strictly prohibited. Furthermore, the misuse of funds collected from buyers or lease-purchasers of future-formed housing is prohibited under Clause 5, Article 8 of the 2023 Law on Real Estate Business.
A Business Cooperation Contract (BCC) can be a legitimate tool for mobilizing resources if it reflects the true nature of the transaction. However, if used to disguise a project transfer before meeting legal conditions, credit risk increases significantly.
Developers should avoid structures that allow a partner to exercise actual control over the project, receive all economic benefits, or perform legal obligations in place of the primary developer. Such transactions may be flagged by banks as disguised project transfers. For sound credit management, a BCC must clearly define the scope of contribution, profit-sharing rights, implementation responsibilities, and management authority.
Before submitting a credit application, developers must perform a self-audit from the perspective of a bank. The goal is to prove project legality, equity compliance, collateral viability, and the validity of repayment cash flows.
This structured approach allows developers to identify bottlenecks early. If gaps in capital or collateral are found, they should be addressed through capital increases, refinancing, or partial project transfers before official bank appraisal.
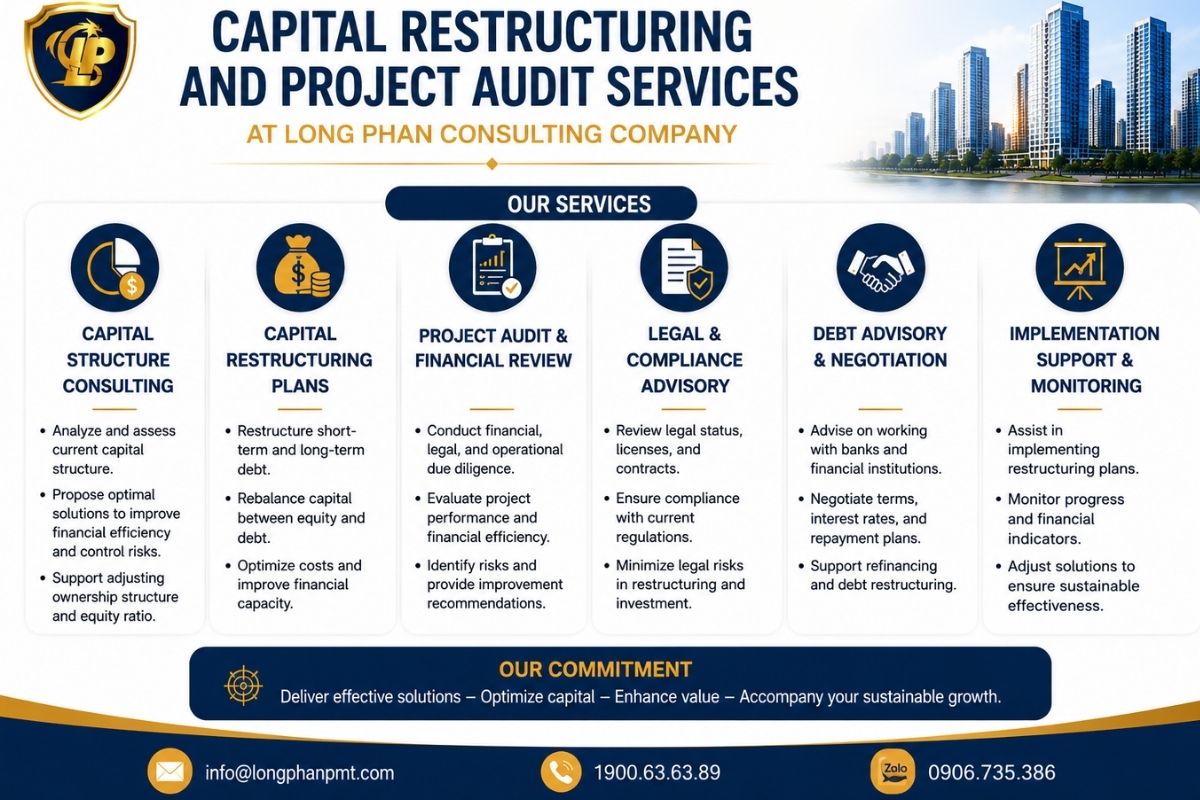
Navigating the intersection of corporate law, real estate regulations, and banking requirements in Vietnam is a complex endeavor that demands high-level precision. Long Phan Consulting Company provides specialized consultancy to help investors audit their financial structures and secure project financing through the following professional services:
To receive a preliminary evaluation of your project’s capital structure and credit potential, please contact our experts. You may submit your project legal files via Email: info@longphanpmt.com or Zalo/WhatsApp: +84 906 735 386.

The due diligence process for “M&A legal documents” goes beyond simply checking paperwork; it also includes strategic valuation, tax risk control, and verification of the target asset’s legitimacy. Early identification of legal blind spots in the transaction structure helps investors prevent the risk of the contract being invalidated or incurring administrative penalties. Potential risks from a corporate and investment law compliance perspective must be eliminated to ensure the absolute protection of the acquisition capital.
Foreign investors are required to register their capital contributions and share purchases before changing shareholders if the transaction results in an ownership stake exceeding 50% of the charter capital. Furthermore, all payment activities related to the purchase and sale of shares by foreign investors must be conducted through accounts in accordance with foreign exchange management laws, except for transactions involving payment in kind as stipulated in Point b, Clause 3, Article 21 of the 2025 Investment Law and Clause 5, Article 35 of the 2020 Enterprise Law.
The sale of assets within an asset deal transaction structure must be approved by the company’s highest governing body based on a percentage of the asset value. For joint-stock companies, the threshold for asset sale transactions requiring approval from the General Meeting of Shareholders is 35% or more of the total asset value as recorded in the most recent financial statement, in accordance with Point d, Clause 2, Article 138 and Point h, Clause 2, Article 153 of the 2020 Enterprise Law.
Investors are required to submit a notification of economic concentration before conducting transactions if the enterprise reaches certain scale thresholds. Specifically, the mandatory notification threshold includes total assets or total revenue in Vietnam reaching VND 3,000 billion or more, or a transaction value of VND 1,000 billion or more, as stipulated in Clause 1, Article 13 of Decree No. 35/2020/ND-CP. Enterprises that violate the regulations by failing to notify before M&A will be fined up to 5% of their total revenue, as stipulated in Clause 2, Article 111 of the 2018 Competition Law.
Investors acquiring equity stakes must require the target company to provide written evidence of a valid offering to existing members. The time limit for existing members to exercise their pre-emptive right to purchase equity stakes before transferring them to outsiders is 30 days from the date of the offering, as stipulated in Point b, Clause 1, Article 52 of the 2020 Enterprise Law. The transfer of capital to outsiders is only legal if the existing members do not purchase or do not purchase all of the shares.
The transferee in Vietnam is obligated to deduct and pay the tax arising from the M&A transaction if the transferor is a non-resident foreign organization or individual. Compliance with this tax payment obligation is mandatory to avoid the risk of tax arrears. If the capital transfer transaction involves tax evasion, the enterprise will be fined from one to three times the amount of tax evaded, depending on the severity of the violation, as stipulated in the 2025 Law on Tax Administration.
The transferee of a real estate project is not required to request the transferor to present the Land Use Right Certificate if the transferring investor has already received a land allocation or lease decision and has fulfilled all financial obligations. However, the real estate project being transferred must have completed land compensation and clearance, the land must not be subject to seizure, and there must be no disputes, in accordance with Clauses 1 and 3 of Article 40 of the 2023 Law on Real Estate Business.
Real Estate Financing in Vietnam is only viable when a developer proves compliant equity, project legality, valid collateral, and verifiable cash flows. Capital restructuring must simultaneously address actually contributed capital, hidden liabilities, and strategic refinancing or partial transfers. Improper standardization can lead to disbursement denials or severe legal risks. Contact our Hotline at 1900636389 for professional support from Long Phan Consulting Company.
📚 This article is provided with professional consultation based on the following legal framework: